A burst pipe insurance claim example can make a stressful emergency easier to understand, but the real outcome often depends on what happens in the first few hours. A pipe can release dozens of gallons of water quickly, soaking drywall, flooring, insulation, furniture, and electrical areas. Fast shutoff, professional drying, and clear documentation can protect both your property and your insurance claim.
Consider a homeowner who returns from a winter weekend away to find water running through a kitchen ceiling. An unheated exterior-wall pipe froze and split, flooding the kitchen and the finished basement below. The homeowner shuts off the main water supply, photographs the damage, contacts their insurer, and calls an emergency restoration team to extract water and begin drying.
The insurer may view this as a sudden and accidental discharge of water, which is commonly covered under many homeowners policies. However, coverage is never automatic. The adjuster will review the policy, the cause of loss, whether reasonable steps were taken to maintain heat, and the extent of damage. The pipe repair itself may be treated differently from damage caused by the released water.
A Burst Pipe Insurance Claim Example, Step by Step
In this scenario, the homeowner reports the loss the same day. They provide the date and estimated time the water was discovered, explain that the home was heated before they left, and share photos showing water beneath the kitchen sink, ceiling staining, and damage in the basement.
An emergency plumber identifies a split supply line in an exterior wall. The line is shut off and repaired to stop the source. A restoration crew documents moisture readings, removes standing water, places drying equipment, and prepares an itemized emergency-service invoice. These records establish a clear timeline: the failure occurred, the water was stopped, and mitigation began without delay.
The insurance adjuster then inspects the property or reviews the contractor’s documentation. If the policy covers the event, the claim may include reasonable costs to mitigate water damage, dry affected materials, remove unsalvageable drywall or flooring, and restore covered areas. It may also include damaged personal property, subject to policy limits, deductibles, and whether the policy provides replacement-cost or actual-cash-value coverage.
The homeowner’s out-of-pocket cost is often the deductible, although this depends on the policy and its endorsements. If mold develops because water remained trapped behind walls, the insurer may scrutinize whether prompt drying occurred and whether mold coverage is limited. That is why emergency mitigation is not simply cleanup. It is a key part of limiting the scope of the loss.
What Insurance May Cover After a Pipe Bursts
Most standard homeowners policies are designed to cover sudden, accidental water damage from plumbing failures. A burst pipe can fall into that category when it is unexpected and the insured has taken reasonable care of the property. For a condo owner, coverage may be divided between the unit owner’s policy and the condominium corporation’s master policy. For landlords and commercial property operators, coverage may also involve business personal property, loss of rental income, or business interruption provisions.
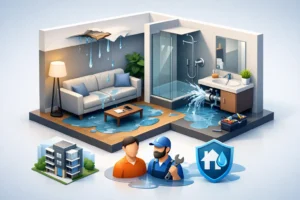
The distinction that matters is often the difference between the damaged pipe and the resulting damage. An insurer may pay for water-damaged cabinets, ceiling repairs, drying, and damaged contents while limiting or excluding the cost to replace an old, corroded, or failed pipe. Policy language controls the decision.
Coverage can become more complicated when freezing is involved. Many policies require owners to maintain heat or shut off and drain plumbing when a building is vacant. If an insurer determines that a property was left without heat during freezing weather, or that a long-standing leak was ignored, it may deny some or all of the claim. A claim involving neglected maintenance is different from a sudden pipe break in a properly maintained building.
Do not assume a denial is inevitable because a pipe froze, and do not assume coverage is guaranteed because water damage is visible. Read the policy, report the loss promptly, and ask the adjuster which policy provision applies to the claim.
What to Do Before the Adjuster Arrives
Your first priority is safety and damage control. Do not wait for an adjuster before taking reasonable steps to stop active water and protect the building. Waiting can turn a limited plumbing failure into extensive structural damage and mold growth.
Take these actions as soon as it is safe to do so:
- Shut off the main water supply or the nearest accessible fixture valve.
- Turn off electricity to affected areas if water is near outlets, panels, appliances, or wiring. If you are unsure, contact a licensed professional.
- Photograph and video the source, standing water, damaged rooms, and affected belongings before moving items when possible.
- Call your insurance company to open a claim and record the claim number, adjuster contact details, and instructions provided.
- Contact an emergency plumber and water damage restoration contractor to stop the failure, extract water, and begin professional drying.
Keep damaged materials until the insurer or adjuster says they can be discarded, unless removal is necessary for health, safety, or emergency mitigation. If drywall, insulation, carpet padding, or cabinets must be removed because they are saturated, document the condition with photos and moisture records first.
Save every invoice, estimate, receipt, and communication. This includes plumbing repairs, emergency water extraction, equipment rental, temporary accommodation, dehumidification, and replacement purchases. If you make a temporary repair, retain the damaged pipe or take detailed photographs of it. The failed component may help establish the cause of loss.
Documentation That Strengthens the Claim
A well-documented file helps the adjuster understand the loss without guessing. It also gives you a reliable record if the claim takes weeks or months to resolve.
Start with a written timeline. Record when the property was last checked, when the damage was discovered, when water was shut off, and when emergency services arrived. For a rental, condo, or commercial building, note who reported the issue and which units or business areas were affected.
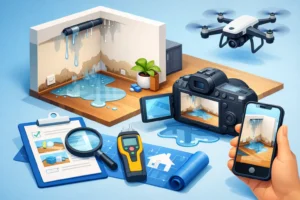
A professional mitigation report is especially useful. It should identify the source of water, affected building materials, moisture readings, equipment used, work performed, and recommended next steps. Thermal imaging, moisture mapping, and daily drying logs can show that water was addressed behind walls and beneath flooring, not merely removed from visible surfaces.
Create a contents inventory for damaged belongings. Include the item description, approximate age, purchase price if known, photographs, and any available receipts. Avoid throwing away damaged contents before documenting them. If you must dispose of unsanitary or severely damaged items, photograph them from multiple angles first.
Common Claim Mistakes That Create Delays
The most costly mistake is delaying mitigation because of uncertainty about coverage. Insurers generally expect policyholders to protect the property from further damage. Leaving wet carpet, wet drywall, or trapped moisture in place can increase the repair scope and create avoidable disputes.
Another mistake is accepting a verbal explanation of coverage without requesting the relevant policy language. Ask clear questions: Is water damage covered? Is there a separate water damage deductible? Is mold coverage limited? Are temporary living costs covered if the home is unsafe? For commercial buildings, ask whether business interruption or loss-of-income coverage may apply.
Avoid signing broad repair agreements before you understand the scope of work and insurer process. Emergency mitigation should proceed quickly, but reconstruction decisions should be documented, itemized, and coordinated with the adjuster where possible. The right approach depends on the severity of damage, the policy, and whether the building can remain safely occupied.
For properties in Toronto and the GTA, GTA Restoration can coordinate emergency plumbing, water extraction, drying, documentation, and property recovery under one response plan. This reduces the handoffs that can slow a claim during an active water emergency.
A burst pipe is disruptive, but it does not have to become a prolonged property crisis. Shut off the water, document the loss, report it promptly, and bring in qualified help to stabilize and dry the structure before hidden moisture creates a second emergency.