Overland Water Coverage and Sewer Backup Insurance
Water can enter a home in several ways, and insurance policies may treat each source differently. Understanding overland water coverage and sewer backup coverage can help homeowners identify potential gaps before flooding or a backup occurs.
Overland water generally refers to freshwater that flows across the ground and enters a property. For example, heavy rainfall, rapid snowmelt, overflowing rivers, and surface runoff can contribute to this type of flooding.
In contrast, a sewer backup involves water or wastewater flowing backward through a sewer, drain, sump system, or plumbing fixture. Although severe storms can contribute to both events, the source of the water differs.
Insurance policies, endorsements, limits, and exclusions vary. Therefore, homeowners should confirm their individual coverage directly with their insurer or licensed insurance broker.
What Is Overland Water?
Overland water is water that travels across the surface of the land before entering a building. For instance, it may collect around foundations, doors, basement windows, window wells, garages, and other low points.
Common conditions that can contribute to overland flooding include:
Heavy or prolonged rainfall
Rapid snowmelt
Overflowing rivers or streams
Surface runoff
Drainage systems that cannot manage the volume of water
Water collecting around foundations and low areas
However, the exact definition used for insurance purposes depends on the policy. Therefore, homeowners should review the wording of their own coverage rather than assuming every type of surface flooding receives the same protection.
What Is a Sewer Backup?
A sewer backup occurs when water or wastewater reverses direction and enters a property through drains, toilets, plumbing fixtures, or related drainage systems.
Heavy rainfall can contribute to some sewer backups when drainage or sewer systems receive more water than they can manage. However, other problems can also cause backups. Therefore, understanding the source can help property owners choose the right next steps.
Blocked Sewer Lines
Grease, debris, damaged pipes, foreign materials, or other obstructions can restrict flow through a sewer line. As the restriction becomes worse, wastewater may have difficulty leaving the property.
Tree Root Intrusion
Tree roots can enter damaged or vulnerable underground pipes and restrict wastewater flow. As a result, a plumbing or sewer inspection can help identify root intrusion and other defects.
Aging or Damaged Sewer Pipes
Older pipes can crack, collapse, shift, or deteriorate. Consequently, these problems may restrict drainage and increase the likelihood of a backup.
Heavy Rainfall and Sewer Capacity
Severe rainfall can place additional pressure on municipal drainage and sewer infrastructure. However, conditions vary by neighbourhood and by the type and capacity of the local system.
Overland Water Coverage vs. Sewer Backup Coverage
The main difference involves the source and path of the water. Overland water coverage generally relates to freshwater that travels across the ground before entering the property. In contrast, sewer backup coverage generally addresses water or wastewater that enters through a sewer, drain, sump system, or related plumbing system.
A single severe storm can create more than one type of water loss. For example, surface water may enter around a basement opening while a sewer system experiences a backup at the same property. As a result, identifying how the water entered the building becomes important.
Because policy definitions vary, the cause of the loss can affect how an insurer evaluates a claim. Therefore, homeowners should understand both types of coverage before a loss occurs.
Does Standard Home Insurance Cover Overland Water?
Homeowners should not assume that a standard home insurance policy automatically includes every type of flood or water damage.
Instead, insurers may offer additional coverage or endorsements for overland flooding, sewer backup, sump pump failure, and other water-related risks. Availability, deductibles, limits, exclusions, and definitions can vary by insurer and property.
The Government of Canada provides additional information about flood insurance and explains why homeowners should understand their policy before a flood occurs. For more information, review the Government of Canada information on overland flood insurance.
What May Sewer Backup Coverage Include?
Sewer backup coverage varies by insurance policy. Depending on the policy and circumstances, coverage may apply to some costs associated with cleanup, damaged building materials, restoration, or damaged contents.
However, homeowners should not assume that every expense receives coverage. Deductibles, limits, exclusions, endorsements, and other policy conditions may affect a claim.
Therefore, ask your insurer or broker specifically about:
Sewer backup coverage limits
Overland flood coverage
Applicable deductibles
Coverage for finished basements
Contents coverage
Sump pump-related losses
Additional exclusions or restrictions
Property Damage From a Sewer Backup
Sewer water can affect flooring, drywall, insulation, cabinets, contents, and other materials. In addition, wastewater may contain contamination. Therefore, property owners should avoid unnecessary contact with affected water and materials.
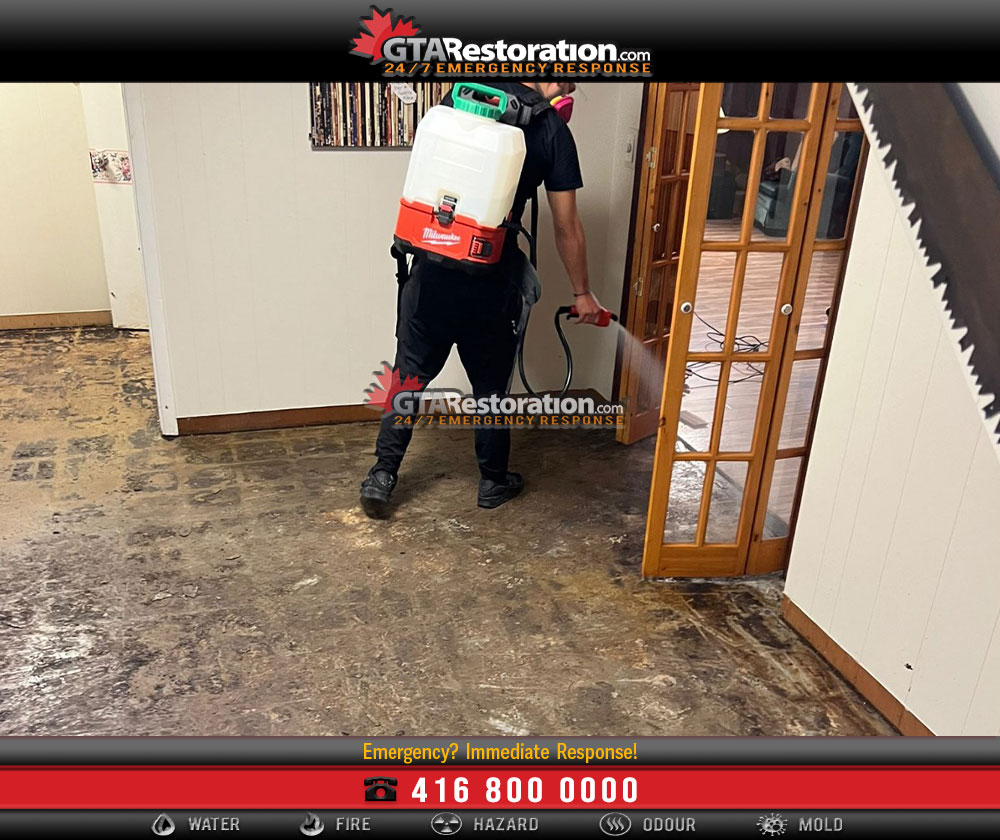
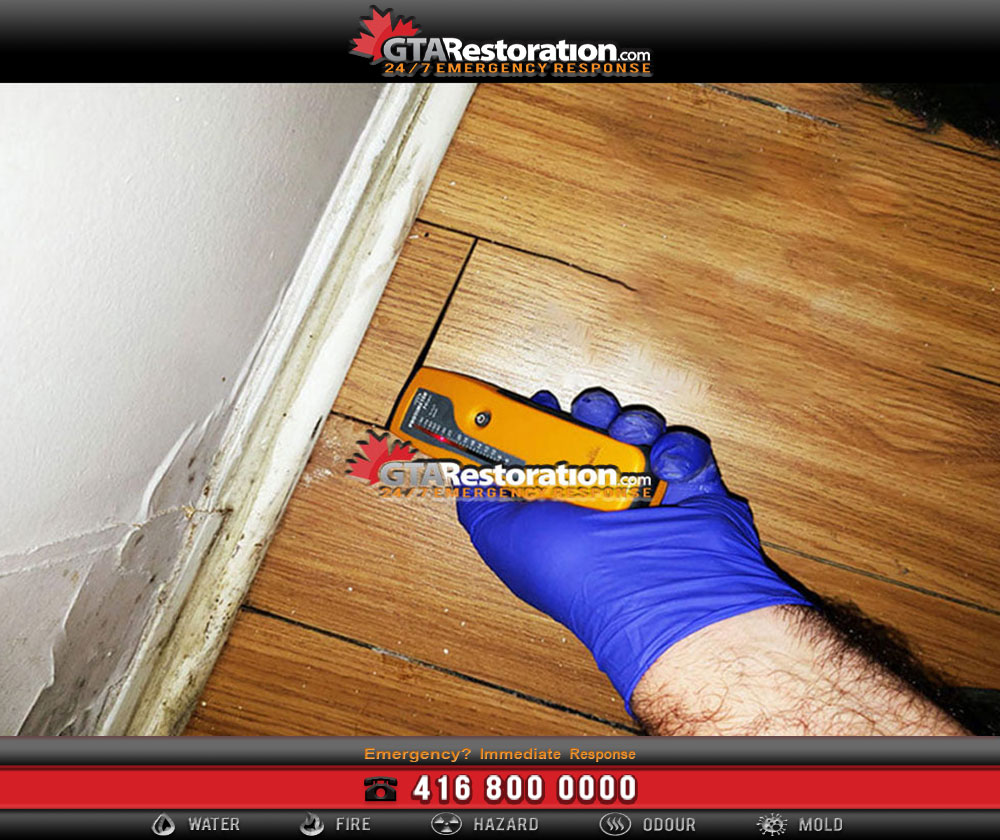
Depending on the extent of the loss, professional restoration may involve water extraction, removal of affected porous materials, cleaning, moisture assessment, structural drying, and restoration.
No preventive measure can eliminate every sewer backup risk. However, homeowners can take practical steps to reduce some common problems.
Maintain Sewer and Drain Lines
Recurring slow drains, unusual plumbing behaviour, or previous backups may justify professional inspection. For example, a plumber can assess the drainage system and identify blockages, damage, or other concerns.
Use Drains Properly
Avoid putting grease, fats, oils, wipes, and other unsuitable materials into household drains or toilets. Otherwise, these materials can contribute to restrictions and blockages.
Consider a Backwater Valve
A backwater valve can help prevent wastewater from reversing through a sewer connection under certain conditions. Therefore, a qualified professional can determine whether a valve is appropriate for the property and install it correctly.
Check Sump Pump Systems
Properties that rely on sump pumps should inspect and maintain the system according to the manufacturer’s recommendations. In addition, some homeowners consider backup power or secondary systems where appropriate.
Manage Water Around the Foundation
Proper grading, drainage, gutters, and downspouts can help direct rainwater away from the building. However, property conditions vary, so drainage improvements should suit the specific site.
What to Do After a Sewer Backup
Safety should come first when wastewater enters a home or business. Therefore, avoid unnecessary contact with contaminated water and affected materials.
Keep People Away From Contaminated Water
First, limit access to affected areas and keep children and pets away from sewage-contaminated water and materials.
Stop Using Affected Plumbing
Next, avoid unnecessary use of toilets, sinks, showers, washing machines, and other fixtures until a professional identifies the problem.
Document the Damage
When conditions allow, take photographs and videos of affected rooms, building materials, and contents before major cleanup begins.
Contact Your Insurer
Then, report the loss according to your insurer’s claims procedures. Ask what documentation they require and keep copies of invoices, estimates, photographs, reports, and other records.
Arrange Professional Cleanup
Finally, arrange appropriate cleanup when needed. Sewage contamination requires additional precautions. A restoration team can assess affected materials, remove contaminated water, clean the area, and begin drying when necessary.
What to Do After Overland Flooding
Overland flooding can create electrical, structural, and contamination hazards. Therefore, avoid entering flooded areas when electrical equipment may be energized or when conditions appear unsafe.
Once conditions allow safe access, document the damage and contact your insurer. Next, water extraction and moisture assessment can help determine which materials require drying, cleaning, or removal.
Good documentation can help your insurer understand the loss and the restoration work performed. Therefore, keep records such as:
Photographs and videos of affected areas
A list of damaged contents
Plumbing or sewer reports
Emergency restoration invoices
Drying and moisture records when available
Repair estimates
Receipts related to the loss
Correspondence with the insurer or adjuster
Ultimately, the insurer determines coverage according to the policy and circumstances of the loss. Restoration documentation can support the claim, but it does not determine whether the insurer will approve coverage.
Review Your Overland Water Coverage Before a Loss
Homeowners can reduce uncertainty by reviewing their overland water coverage before severe weather or a plumbing emergency occurs. In particular, ask about overland flooding, sewer backup, sump pump failure, deductibles, coverage limits, exclusions, and optional endorsements.
Property risk can also change over time. For example, renovations, basement finishing, drainage changes, aging plumbing, and previous water losses may justify another discussion with an insurance professional.
UNDERSTANDING OVERLAND WATER & SEWER BACKUP COVERAGE
Everyone knows that climate change is causing more frequent and more intense weather events and many of those events are causing water damage to Canadians homes and belongings.
Most standard home insurance policies cover sudden and accidental water damage from things like a burst pipe or a popped waterbed but damage from water that enters your home from other sources like a heavy rainfall, a sewer backup or a sump pump failure is not automatically covered.
So we’ve added overland water and sewer backup coverage as an optional add-on so you can get coverage beyond what’s included in your basic home insurance.
Your standard home insurance policy normally includes coverage for:
Damage caused by sudden or accidental water escape from household sources like burst interior water pipes, hot water tanks, waterbeds, aquariums, swimming pools, and hot tubs.
Overland water and sewer backup coverage protects your property from:
Damage caused by sudden accumulation of ground water or surface water, such as excessive rain, overflowing rivers, spring run-off, or melting snow. (Note: This excludes damage caused by saltwater, including tidal waves and tsunamis.)
Damage to your property caused by the rupture or escape of water from a sewer, drain, sump pump, or septic system.
Damage caused by the escape of water resulting from a collapse, rupture, leak, or break in your service line. Your service line is the exterior water line, for which you are liable, that connects to your home from public water supplies, private wells, retention ponds, or cisterns, including pipes that drain water away from your home or any other structure.
Need Flood or Sewer Backup Cleanup?
GTA Restoration provides water extraction, sewage cleanup, moisture assessment, structural drying, and restoration throughout Toronto and the GTA.
For an active water or sewer backup emergency, avoid contaminated areas and call for professional assistance.
Overland flooding and sewer backups can both cause serious property damage, but they happen for different reasons. Therefore, understanding the source of the water can help homeowners review their insurance coverage, plan preventive measures, and respond properly after a loss.
Know the Difference Between Flooding and Sewer Backup
Overland flooding usually involves surface water entering a property after heavy rain, snowmelt, overflowing rivers, or other freshwater flooding. In contrast, sewer backup happens when wastewater or drainage systems reverse flow and push contaminated water back through drains, toilets, or other plumbing fixtures.
Review Your Insurance Policy
Standard home insurance may not automatically cover every type of flooding or sewer backup. Therefore, review your policy with your broker or insurer before a loss occurs. Coverage often depends on the insurer, policy wording, endorsements, exclusions, limits, and property risk.
Document Flood and Sewer Damage
When conditions are safe, take photographs and videos before major cleanup begins. In addition, keep restoration invoices, plumbing reports, damaged-content records, estimates, receipts, and other documents that may support an insurance claim.
Protect Basements and Lower Levels
Basements and lower-level rooms face greater risk during heavy rainfall and sewer-system overloads. For example, moving valuables off the floor, using water-resistant storage, maintaining sump systems, and monitoring drainage can help reduce potential losses.
Consider a Backwater Valve
A properly installed backwater valve can help reduce the risk of wastewater flowing backward into a property through drains and plumbing fixtures. However, homeowners should have a qualified professional determine whether a valve suits their property.
Maintain Drains and Sewer Lines
Tree roots, grease, debris, pipe damage, and aging sewer lines can contribute to backups. As a result, periodic inspection and maintenance can help identify problems before they become major emergencies.
Watch Weather and Flood Conditions
Heavy rain, rapid snowmelt, and overwhelmed municipal drainage systems can increase flood and sewer-backup risks. Therefore, property owners should monitor local weather alerts and take preventive action when severe rainfall is expected.
Insurance Coverage Depends on the Policy
Overland water coverage and sewer backup protection vary between insurers and policies. Therefore, property owners should confirm what their insurance includes, what endorsements are available, and what exclusions or limits apply.
Flood and Sewer Backup Restoration Toronto
GTA Restoration provides water extraction, sewage cleanup, structural drying, documentation, and property restoration for flood and sewer-backup losses throughout Toronto and the GTA.
Need Help After Flooding or a Sewer Backup?
Nationwide, Local Pricing
GTA Restoration offers local flood & water damage repair, mold removal/remediation, asbestos removal/abatement, fire/smoke damage repair services and much more.
Overland water is surface water that enters a property after events such as heavy rainfall, snowmelt, or overflowing freshwater sources.
What Is a Sewer Backup?
A sewer backup occurs when wastewater or drainage systems reverse flow and send contaminated water back through drains, toilets, or other plumbing fixtures.
Does Standard Home Insurance Cover Overland Flooding?
Not always. Coverage varies by insurer, property risk, policy wording, limits, and exclusions. Therefore, homeowners should confirm their specific coverage with their insurer or broker.
Does Home Insurance Cover Sewer Backup?
Sewer backup protection may require additional coverage. As a result, property owners should review their policy and confirm the applicable limits, deductible, and exclusions.
Can a Backwater Valve Help Prevent Sewer Backup?
A properly installed backwater valve can help reduce the risk of wastewater flowing backward into the property. However, a qualified professional should determine whether one suits the property.
What Should I Do After a Flood or Sewer Backup?
First, put safety first and avoid contaminated water. Next, document the damage, contact your insurer, and arrange professional water extraction and cleanup when needed.
Need flood or sewer backup cleanup? Call 416-800-0000.









You must be logged in to post a comment.